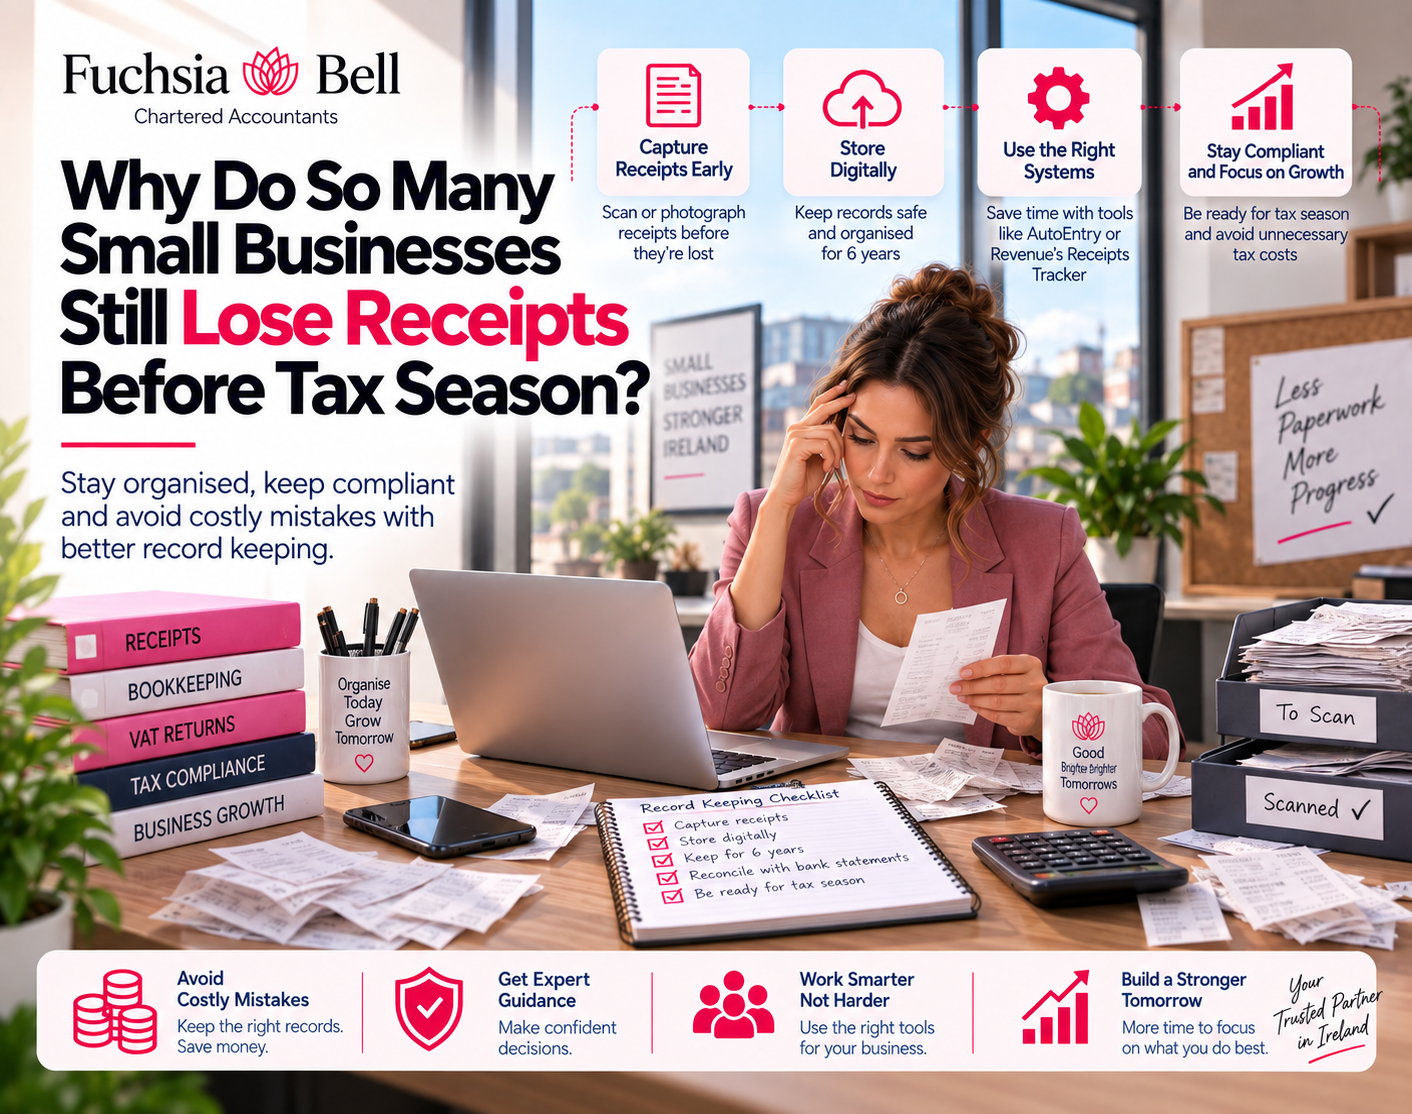
A thermal paper receipt left in a car, a wallet, or on a sunny desk can fade to a blank strip within a few months, long before Revenue’s six-year retention requirement even gets close to expiring. Most lost-receipt problems aren’t carelessness. They’re a paper format that was never built to survive the length of time Irish tax law actually requires it to.
The six-year figure isn’t a suggestion. It’s how long Revenue can revisit a transaction, and it applies to income tax, corporation tax, VAT, and every document behind a tax return, not just the headline figures a business reports each year.
Why Paper Receipts Specifically Fail
Thermal printing, the kind used by most retail tills and fuel pumps, works by heat-sensitive coating rather than ink, which means heat, light, and even friction can degrade the print long before the paper itself wears out. A receipt that looks perfectly legible on the day of purchase can be an unreadable blank sheet within months, with no warning and no way to reprint it later. Proper bookkeeping practice treats this as a format problem to solve immediately, not a filing habit to improve eventually, since the physical evidence itself has a shorter shelf life than the record-keeping requirement around it.
What Revenue Actually Requires You to Keep
The obligation covers sales invoices and receipts issued, purchase invoices and supplier statements, bank statements and lodgement slips, VAT returns and their supporting calculations, and the documents underpinning an annual income tax return or corporation tax filing. Records need to be retained for six years from the date of the transaction they relate to, and disposing of anything earlier requires written Revenue permission first, not just a judgement call that it’s probably safe to shred.
The Cost That Shows Up Even Without an Audit
Poor record keeping doesn’t need a Revenue intervention to cost money. An expense without a receipt generally can’t be safely claimed. VAT on a purchase can’t be reclaimed without a valid invoice to support it, which quietly inflates the VAT return actually paid over. Capital allowances go unclaimed when asset purchase records are incomplete, and legitimate deductions simply get forgotten because nobody wrote them down when the expense happened. This cost arrives every single year, audit or not, through tax quietly overpaid rather than tax penalised.
What Happens When Revenue Actually Asks
An intervention letter requesting documentation from three or four years earlier catches a lot of businesses off guard. A business with organised digital records can usually respond within days. One relying on mixed paperwork, a departed employee’s memory, or incomplete files faces weeks of reconstruction and a materially less comfortable conversation. Without adequate records, Revenue can raise an assessment based on its own estimate of what’s owed, and the burden shifts to the business to disprove that figure rather than Revenue having to prove it. Getting tax services support at that stage is considerably harder and more expensive than having the records in order before the letter ever arrives.
A Free Tool Most Businesses Don’t Know Revenue Offers
Revenue’s own Receipts Tracker, built into ROS, lets a business store a digital copy of receipts directly, and Revenue treats a legible, retrievable digital copy as fully equivalent to the paper original. Most small business owners have never used it, and it sits well below what a proper bookkeeping and expense-capture system like AutoEntry actually does, automatic categorisation, OCR-based data extraction, and integration with the accounts rather than a static digital filing cabinet, but it’s worth knowing the baseline option exists at all.
Digital Records Change the Economics, Not Just the Compliance Picture
Manual receipt processing is estimated to consume 20 to 30 hours a month for a mid-sized business, translating to a real labour cost most owners never actually calculate against the price of a proper system. A broader look at how digitising day-to-day financial admin changes the underlying cost structure of a small Irish business is covered on geroconnor.info.
Companies Face a Sharper Edge Than Sole Traders
For an incorporated business, failing to maintain proper accounting records isn’t just a tax risk. Under Section 285 of the Companies Act 2014, it’s a criminal offence in its own right, separate from whatever Revenue penalty might also apply. Emails count as company records too where they contain a board decision, a contract, or financial information, and deleting them to sidestep retention obligations doesn’t remove the obligation, it can constitute destruction of records instead. Getting company secretarial services guidance on what actually needs retaining, and for how long, matters more for a limited company than the tax exposure alone would suggest.
Frequently Asked Questions
Are scanned or photographed receipts acceptable to Revenue?
Yes, provided the digital copy is legible and retrievable for the full retention period, Revenue treats it as equivalent to the paper original.
Can I dispose of records once my tax return for that year has been filed?
No. Filing the return doesn’t end the retention obligation. Records still need to be kept for six years from the date of the underlying transaction, not from the filing date.
Do bank statements count as adequate proof on their own, without the actual receipt?
Generally no. A bank statement shows that a payment happened but not necessarily what it was for or whether it qualifies as a valid business expense, so the underlying invoice or receipt is still needed.
What happens if I genuinely can’t locate a receipt for a past expense?
The expense becomes much harder to defend if queried, and Revenue may disallow it entirely without supporting documentation, regardless of how legitimate the underlying purchase actually was.
Does the six-year rule apply the same way to a sole trader as a limited company?
Yes, the six-year retention period applies broadly across both structures, though a limited company carries the additional Companies Act obligation on top of the tax-related retention requirement.
Fixing the Format Before It Fixes the Business’s Attention
Most businesses that lose receipts aren’t disorganised generally, they’re relying on a physical format that was never designed to last as long as the law requires it to. Moving that problem into a digital system before tax season, not during it, is what actually closes the gap. A fuller picture of how online chartered accountants work with small businesses on ongoing record keeping is covered on geroconnor.info as well.