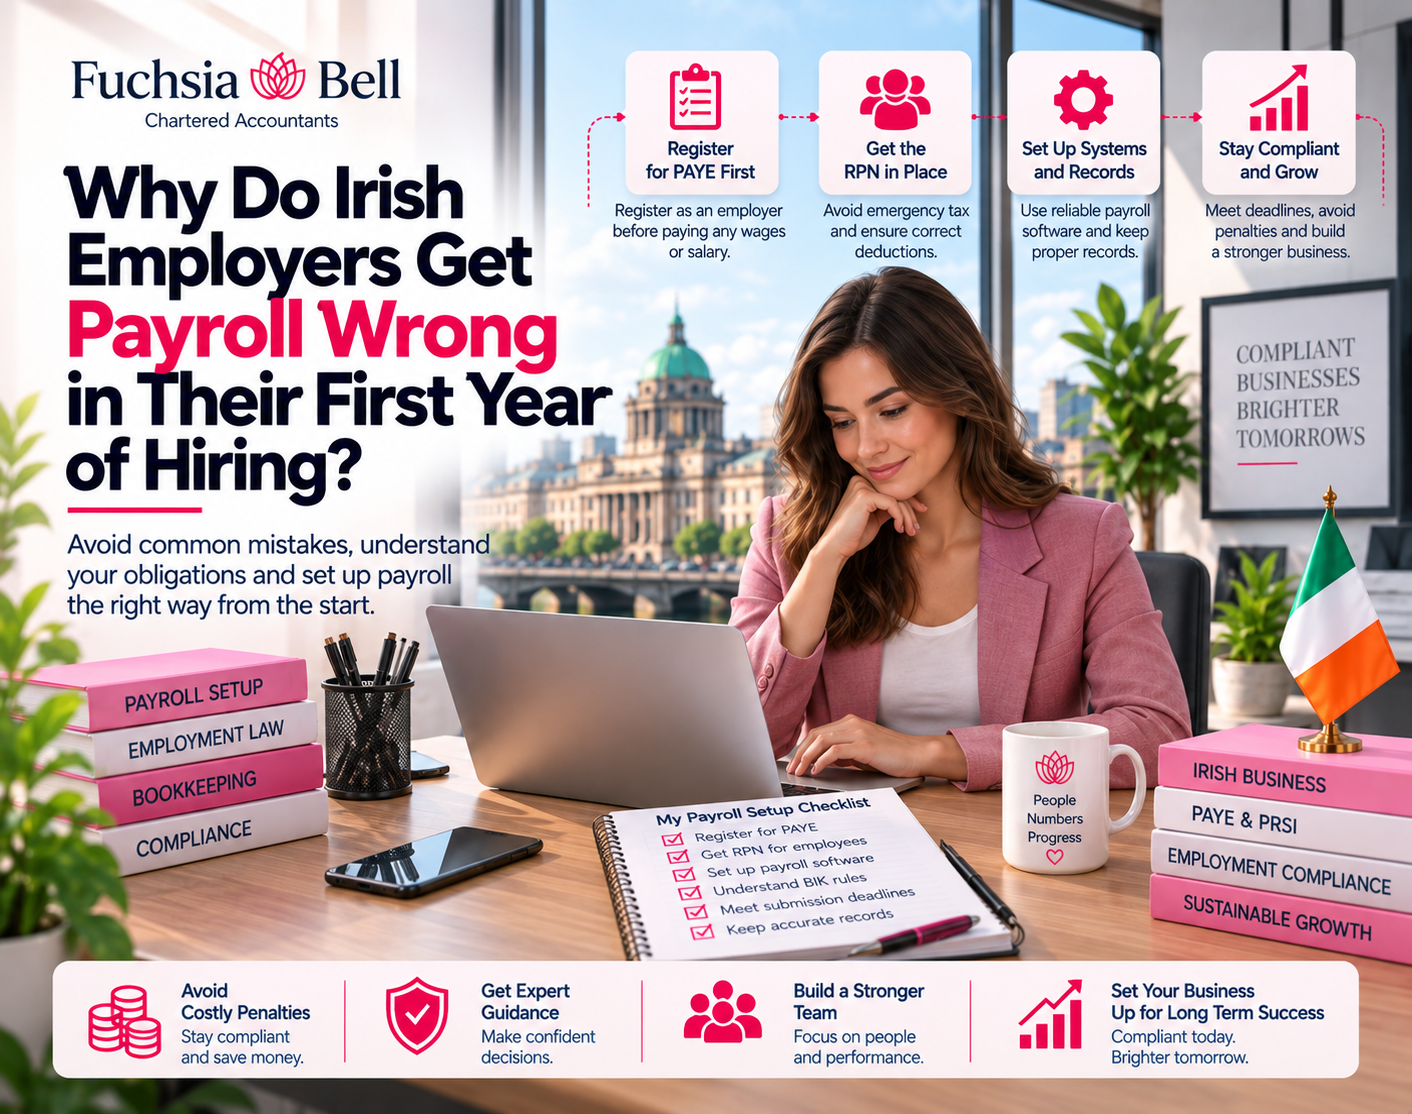
PAYE registration has to happen before the first wage or salary payment goes out, not after. That single ordering mistake, paying someone first and registering as an employer afterward, causes more first-year payroll problems than almost anything else, because it triggers a chain of smaller errors that are harder to unwind than they would have been to avoid.
Most of what goes wrong in a first year of hiring isn’t a calculation error. It’s a sequencing error: doing something in the wrong order, or assuming a rule applies the way it did for a friend’s business rather than checking it directly.
The Trigger Most First-Time Employers Miss
Hiring an employee triggers PAYE registration. So does a director taking a salary from their own company, even a company with no other staff at all. Many first-time company directors assume registration only matters once there’s an actual employee on the books, and pay themselves for months before realising the same rule applied to their own wages from day one. Genuine contractors invoicing for services, and domestic workers paid under €40 a week, generally fall outside this trigger, but a director’s own pay never does. Getting payroll registration sorted before the first payment, rather than the first employee, is the distinction that actually matters.
Registering After the Fact Got Harder in 2026
Since 2 March 2026, a PAYE employer registration can only be backdated by one period through ROS. Before that change, a longer delay in registering was still a hassle but a relatively simple one to fix retroactively. Now, anything beyond one period requires a MyEnquiries case explaining the gap, and potentially a voluntary disclosure to Revenue depending on how long the business was paying wages unregistered. A start-up that delays registration by even a few months longer than it used to be able to now faces a materially more involved process to correct it.
Running Payroll Without an RPN Defaults to Emergency Tax
Without a Revenue Payroll Notification on file for a new employee, the payroll system has no instruction on what credits or rate band to apply, so it falls back to emergency tax, a deliberately punitive default designed to be corrected rather than to be accurate. New employers frequently run a first payroll before the RPN comes through, assuming it will sort itself out, and the employee ends up short on their first few payslips as a result. Requesting the RPN as soon as an employee is hired, not on the day payroll actually runs, closes most of this gap before it opens. Where tax services advice comes in useful here is less about the calculation and more about the timing of the request itself.
Misclassifying a Worker as a Contractor
Treating someone as a contractor when the working relationship actually looks like employment, set hours, a single client, tools and equipment supplied by the business, is one of the most consequential first-year mistakes, because it isn’t just a payroll error. Revenue and the Workplace Relations Commission can both reclassify the relationship after the fact, triggering backdated PAYE, PRSI, and potential penalties on payments that were never run through payroll in the first place. This comes up constantly for a growing consultants practice bringing on its first help, where the line between a genuine subcontractor and what’s actually an employee isn’t always obvious from the outside.
The Benefit-in-Kind Blind Spot
A company car, a phone used partly for personal calls, a gym membership paid by the business, all of these can count as a taxable Benefit-in-Kind that needs to run through payroll, not just as a business expense on the accounts. First-time employers frequently treat these as simple perks rather than something with its own reporting obligation, and BIK omissions tend to surface later as a Revenue query rather than something caught in year one. A small business offering even one non-cash benefit to staff needs this built into payroll from the first instance, not added retroactively once the value adds up.
Payslip Requirements Are Not Optional
Every employee is legally entitled to a payslip showing gross pay, every deduction, and net pay, for every single pay period. Missing or incorrect payslips aren’t just a documentation gap. They’re something an employee can report directly to the Workplace Relations Commission, and a pattern of poor payroll records makes it far harder to defend the business if a dispute over pay ever arises. Keeping this alongside proper company secretarial services record-keeping from the outset avoids a scramble to reconstruct a year’s worth of payslips from bank statements later.
Auto-Enrolment Adds a New Employer Obligation From 2026
Beyond the standard PAYE, USC, and PRSI deductions, employers now have a fourth payroll responsibility for qualifying staff not already in a workplace pension: Ireland’s auto-enrolment scheme, which started on 1 January 2026. The employer’s own contribution starts at 1.5% of gross pay in the scheme’s first three years, on top of whatever the employee and the State contribute. A broader look at how payroll obligations fit into an Irish business’s overall tax and compliance position is covered on geroconnor.info, since auto-enrolment is one part of a bigger first-year picture rather than an isolated deduction.
Frequently Asked Questions
Can I run payroll myself using software instead of registering with Revenue?
No. Payroll software calculates deductions correctly, but it doesn’t replace the underlying obligation to register as an employer with Revenue before any payment goes out.
What happens if an employee’s RPN never arrives?
The employee should register their job through Revenue’s myAccount service if they haven’t already, since the RPN is generated once that registration is in place, and payroll can be corrected retroactively once it comes through.
Does a single director-only company need full payroll software?
Yes, generally. Even a sole director drawing a salary needs correctly calculated PAYE, USC, and PRSI, which requires the same registration and reporting as a company with multiple staff.
How often does payroll need to be submitted to Revenue?
On or before every payday, under PAYE Modernisation. There’s no monthly batching allowance that lets submissions lag behind the actual pay date.
Is a verbal agreement enough to establish someone as a contractor rather than an employee?
No. Classification is based on the actual working relationship, hours, control, equipment, exclusivity, not on what the arrangement is called in a contract or conversation.
Building Payroll Around the Sequence, Not Just the Numbers
Almost every mistake covered here traces back to doing something in the wrong order: paying before registering, running payroll before the RPN lands, treating a worker as a contractor without checking the relationship first. Getting the sequence right in the first few weeks of hiring avoids the vast majority of what causes first-year payroll problems, regardless of how good the actual payroll calculations end up being. A fuller picture of how online chartered accountants work with employers hiring their first staff is covered on geroconnor.info as well.